Every time the Federal Reserve meets, real estate investors brace for the headline. Will rates go up, down or sideways, and what does that mean for the property they own or want to buy? The honest answer is that the Fed matters a great deal, but not in the direct, mechanical way many people assume. Understanding the actual chain of cause and effect, from policy rate to Treasury yields to cap rates, helps investors avoid both panic and complacency.
What the Fed controls, and what it does not
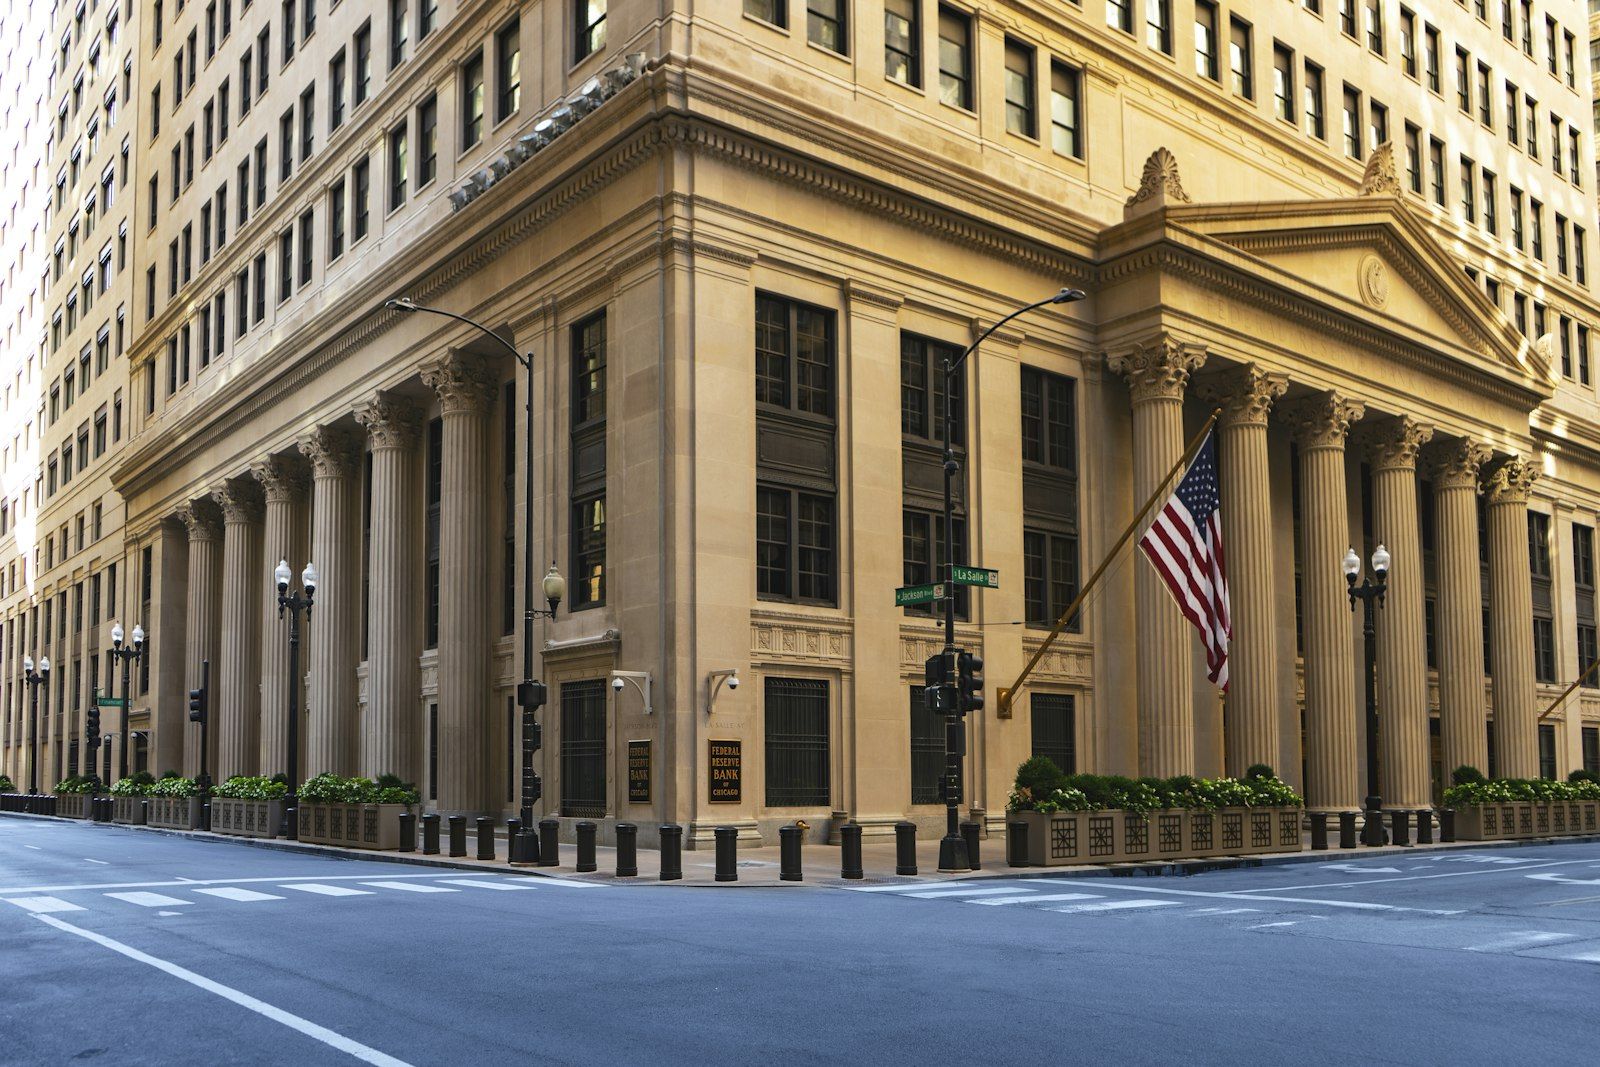
The Federal Reserve's main policy tool is the federal funds rate, the target rate at which banks lend reserves to each other overnight. It is a very short-term rate. The Fed also influences longer-term rates through its balance sheet, by buying or allowing to run off Treasury bonds and mortgage-backed securities, and through its guidance about where policy is heading.
Commercial real estate, however, is a long-duration asset. Investors and lenders price it against long-term benchmarks, most commonly the 10-year Treasury yield. The 10-year reflects market expectations about future short-term rates, inflation and economic growth, along with a term premium. When the Fed cuts its policy rate, the 10-year may fall, stay flat or even rise if markets expect inflation to pick up. That is why a Fed cut does not automatically make property more valuable.
The Fed moves the front end of the yield curve. Real estate lives at the long end, and the long end has a mind of its own.
A quick refresher on cap rates
The capitalization rate is a property's net operating income (NOI) divided by its value or price. It works as a rough measure of the unlevered yield an investor accepts in exchange for owning the asset. Rearranged, the formula shows why cap rates matter so much: value equals NOI divided by the cap rate.
Consider a $2 million property producing $140,000 of NOI. That implies a 7% cap rate. Now watch what happens to value if NOI stays the same but the market cap rate shifts.
| Market cap rate | NOI | Implied value | Change from 7% |
|---|
| 6.0% | $140,000 | $2,333,000 | +16.7% |
| 6.5% | $140,000 | $2,154,000 | +7.7% |
| 7.0% | $140,000 | $2,000,000 | 0% |
| 7.5% | $140,000 | $1,867,000 | -6.7% |
| 8.0% | $140,000 | $1,750,000 | -12.5% |
The math is unforgiving at lower cap rates. Moving from 4% to 5% on the same income cuts value by 20%. That sensitivity is why the rate environment commands so much attention.
$140Killustrative NOI held constant
-12.5%value change if cap rate moves from 7% to 8%
-20%value change if cap rate moves from 4% to 5%
The spread: why the link is not one-for-one
If cap rates simply equaled the 10-year Treasury yield plus a fixed amount, forecasting property values would be easy. In reality, the spread between cap rates and Treasuries expands and contracts over time. Historically, that spread has often been compared with its long-run average to gauge whether real estate looks cheap or expensive relative to bonds.
Several factors move the spread:
- Growth expectations. If investors expect strong rent growth, they accept a lower initial yield, compressing the spread.
- Risk appetite. In periods of economic stress, investors demand more compensation for holding illiquid property, widening the spread.
- Capital availability. When lenders pull back, fewer buyers can compete, and cap rates tend to drift up even if Treasury yields are stable.
- Property type and location. Spreads differ between sectors, such as industrial versus office, and between gateway and secondary markets.
Because the spread can absorb part of a rate move, cap rates usually adjust more slowly and less dramatically than Treasury yields. When rates rise quickly from very low levels, as they did in 2022 and 2023, the spread can compress sharply at first, then cap rates catch up gradually as transactions reprice. Appraisal-based indices often lag the actual market for the same reason.
Financing: where rates hit investors fastest
Even when cap rates are slow to move, higher borrowing costs affect investors immediately. The key concept is leverage. When a property's cap rate is above the interest rate on its debt, borrowing amplifies returns, which is called positive leverage. When debt costs more than the property yields, borrowing drags returns down.
Lenders also size loans using the debt service coverage ratio (DSCR), which compares NOI with annual debt payments. Using our $140,000 NOI example, a lender requiring a 1.25x DSCR will allow up to $112,000 in annual debt service. At a higher interest rate, that same payment supports a smaller loan, meaning buyers need more equity. Less available leverage reduces what buyers can pay, which puts upward pressure on cap rates.
Investor tip
When underwriting, stress test the deal at an exit cap rate at least 50 to 100 basis points above today's going-in rate, and model refinancing at a higher interest rate than you currently pay. If the deal only works when rates fall, it is a rate bet, not a real estate investment.
How fundamentals can offset rate pressure
Rates are only half the valuation equation. NOI is the other half, and it can grow. If rents rise 4% a year and expenses stay contained, NOI growth can offset a meaningful portion of cap rate expansion over a multi-year hold. Returning to the example: if NOI grows from $140,000 to roughly $163,000 over four years, the property would be worth about $2.04 million even at an 8% cap rate, slightly above the original $2 million purchase price.
This is why sector and market selection matter so much in a higher-rate environment. Properties with short lease terms that can reprice to market, located in areas with strong demand and limited new supply, are better positioned than assets locked into long leases with fixed rents or facing structural headwinds.
The bottom line
The Fed influences property values, but through a chain of links rather than a single lever. Policy shapes expectations, expectations shape long-term yields, yields and credit conditions shape cap rates, and cap rates combined with NOI determine value. Investors who understand each step can read Fed headlines more calmly, underwrite more conservatively and focus on what they can actually control: buying assets where income can grow, at prices that still make sense if rates do not cooperate.
 Market Insights